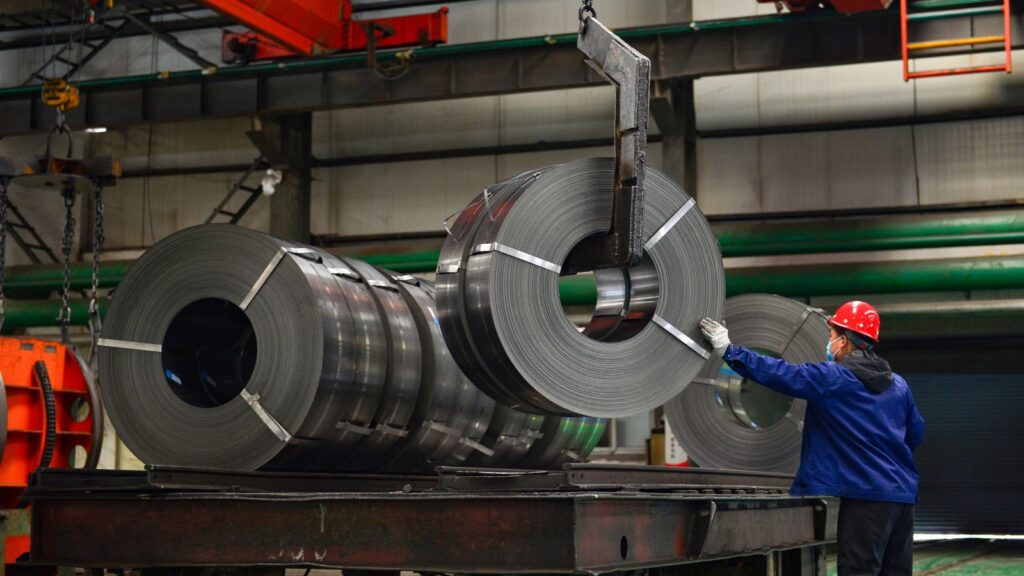
Canada’s steelmakers are searching for replacement orders, and increasingly the next customer is on their own side of the border. Energy projects, construction sites and domestic manufacturers are becoming central to the industry’s response to American tariffs.
Canadian steel shipments to the United States fell 60% during 2025, according to the Canadian Steel Producers Association, as reported by Reuters on October 16, 2026. Mills are competing for Canadian business with support from federal purchasing rules and import restrictions. But finding new customers is not the same as repairing the damage. Algoma’s financial results still show heavy losses, while proposed cuts at Stelco underline how uneven the adjustment remains. A stronger home market is offering some relief—not yet a return to security.
The Tariff Shock Changed the Economics of Selling South
The turning point came on June 4, 2025, when the United States doubled its additional steel import tariff from 25% to 50%. Washington presented the increase as a measure to protect American production and national security. For Canadian mills accustomed to serving customers across the border, it imposed a formidable price obstacle. An illustrative US$1,000 shipment subject to the full 50% duty would attract US$500 in tariff before other charges, changing the economics of a previously routine sale.
The damage extended beyond individual contracts, although mills did not lose production as quickly as they lost exports. In its April 29, 2026, assessment, the Bank of Canada said steel output and employment had declined less severely than exports, partly because government measures were supporting domestic production. That gap helps explain the turn toward Canadian buyers. A mill can retain work by selling more at home even when its American business shrinks, though keeping production running does not guarantee every shift or restore every lost job.
Canada Was Importing Much of the Steel It Needed
Canada’s challenge contains an apparent contradiction: it is a steel producer that has relied heavily on imported steel. Federal estimates put Canadian steel mill production at 12 million metric tonnes in 2024, while the domestic market consumed 13.8 million tonnes. Canadian mills supplied only 5.5 million tonnes of that home market. Imports filled the remaining 8.3 million tonnes, creating a sizeable pool of business that local producers could potentially contest as American orders disappeared.
There are signs of movement. A separate United Steelworkers calculation reported by Reuters put domestic producers’ share of Canadian steel use at 51% in 2025, compared with 41% in 2024. That is a gain of 10 percentage points, not proof that total demand surged. Market share can improve when imports retreat, when domestic deliveries increase, or both. Nor can every imported product automatically be replaced by a Canadian equivalent. The opportunity is substantial, but mills still need to match the specifications, quantities and delivery schedules that Canadian customers require.
Federal Buying Rules Are Creating a Route to New Orders
Ottawa is trying to turn its purchasing power into business for Canadian mills. Rules introduced on December 16, 2025, require Canadian steel, aluminum and wood products in qualifying federal construction and defence procurements worth at least C$25 million. The requirement applies where the relevant materials total at least C$250,000 and Canadian supply is available. It reaches through the supply chain rather than stopping at the main contractor, making material sourcing part of the procurement decision.
For a company bidding to build a federal facility, that changes the questions asked before an order is placed. Using a Canadian intermediary is not the same as using Canadian-produced steel. The policy could help mills compete for work that might otherwise use imported material, while giving fabricators a reason to establish domestic supply relationships. Yet a purchasing rule is not a booked shipment. Projects still need funding, tenders and construction schedules, and suppliers must meet the required standards. The benefit becomes tangible when purchase orders reach a mill’s production schedule.
Import Restrictions Are Giving Local Mills More Space
Federal purchasing is only part of the effort to redirect business. Canada also tightened steel import quotas effective December 26, 2025. For covered products from countries without a Canadian free-trade agreement, the tariff-free allowance was reduced to 20% of 2024 import levels. For free-trade partners other than the United States and Mexico, it fell to 75%. Covered imports exceeding the allowances face a 50% surtax. The system now runs through June 27, 2027; U.S. and Mexican-origin steel is exempt from these quotas, though other trade measures can apply.
These restrictions are intended to give Canadian producers more room in their own market when access to American buyers is constrained. They also create a balancing problem. A Canadian manufacturer purchasing steel needs the correct grade at a competitive price, not simply fewer foreign suppliers. Ottawa’s tariff-relief framework recognizes that some inputs cannot be sourced domestically. The practical test is whether protection helps mills win sustainable business without leaving Canadian steel users facing unavailable materials, costly delays or reduced competitiveness of their own.
Algoma’s Plate Strategy Shows Progress Alongside Heavy Losses
Algoma Steel offers a concrete example of the turn toward Canadian buyers. In its July 29 financial release, the company described a strategy centred on steel plate and domestic infrastructure, construction and defence demand. It reported a second consecutive quarter of record plate sales. Its average net selling price per ton also rose 20.2% from a year earlier, reflecting a shift in the products it sold rather than evidence that all steel prices had risen equally.
The wider accounts were much less encouraging. Revenue for the quarter ended June 30, 2026, fell to C$267.5 million from C$589.7 million a year earlier, and the company recorded a C$96 million net loss. Those numbers show why stronger demand for one product cannot be treated as a complete recovery. Algoma is simultaneously changing its production technology and rebuilding its customer mix. For employees, the important question is whether promising plate orders eventually support a financially stable operation, not simply whether management can point to an improving sales category.
Tenaris Is Building Products for Canadian Energy Customers
At its Sault Ste. Marie operation, Tenaris is pursuing a more targeted version of the domestic strategy. On September 30, 2026, the company announced Canadian production of TN 95EY, a steel grade for pipe used in demanding oil and gas wells. The product is designed for high-pressure and high-temperature conditions, including applications in Western Canada’s Montney and Duvernay formations. Rather than simply redirecting an existing export, the company is adapting production to the requirements of customers operating inside Canada.
The effort follows a C$306 million joint investment announced in May 2026 with the federal and Ontario governments to modernize and expand the facility. That is an investment commitment, not a measure of completed sales. Nevertheless, it illustrates how domestic demand can justify new manufacturing capabilities. A pipe designed for a specific drilling environment offers a different competitive proposition from a standard steel shipment seeking any available buyer. Tenaris’s example also helps explain why the industry’s fortunes vary: an energy-focused pipe operation serves a different market from a mill selling sheet for manufacturing.
Data-Centre Construction Is Already Using Canadian Steel
The domestic shift is visible in the buildings going up around Regina. Bell says structural steel for its Saskatchewan data-centre campus is being milled by InterPro Pipe and Steel in Regina, with buildings manufactured at Prairie Steel’s plant in Clavet. On October 1, The Canadian Press reported that three of the project’s four data halls had been framed and roughly 500 workers were on site. Those are tangible links between a technology investment and Canadian industrial employment.
The first phase has a planned capacity of 300 megawatts. A proposed 900-megawatt expansion would bring the total to 1.2 gigawatts, but Bell says construction of that expansion depends on approvals and a commercial agreement with a tenant. Existing work and future possibilities should therefore be counted separately. Even with that qualification, the supply chain offers a useful example: Canadian steel is being turned into building components by Canadian manufacturers and assembled locally. That creates demand across several businesses rather than at a mill alone.
Stelco’s Planned Layoffs Show How Uneven the Shift Remains
The picture is considerably darker at Stelco. In late September, the company announced plans to cut up to 500 jobs at its Hamilton Works and Lake Erie Works facilities. A company letter reported by The Canadian Press on October 13 said Canadian exports of cold-rolled and coated steel to the United States had fallen 58% in the second quarter of 2026 compared with the 2024 quarterly average. That figure concerns particular steel products, not the entire industry.
Stelco says weaker demand and continued imports justify the cuts; Ottawa disputes whether they comply with employment commitments made when Cleveland-Cliffs acquired the company in 2024. On October 16, Industry Minister Mélanie Joly said the government was exploring options including nationalization. That was not an announcement of a completed takeover. For affected families, the argument about market shares is overshadowed by a more immediate uncertainty: whether their jobs will remain. Stelco’s experience shows why improving national sales indicators cannot establish that every plant, product line or community is recovering.
Government Financing Is Buying Time for the Adjustment
Businesses caught in the metals trade dispute are also getting access to financing. On May 4, 2026, Ottawa announced a C$1 billion Business Development Bank of Canada program for tariff-affected businesses, alongside C$500 million in additional funding for the Regional Tariff Response Initiative. The measures extend beyond steel mills to businesses in affected manufacturing supply chains. For a smaller company waiting for customers to replace cancelled orders, access to working capital can make the difference between continuing operations and an immediate cash shortage.
Financial assistance serves a different purpose from domestic procurement. A loan can help a company manage bills, maintain capacity or adapt its operations, but it does not establish that customers will buy its output at profitable prices. Borrowed money must also be repaid under the applicable terms. The strongest outcome would combine temporary financial breathing room with lasting orders from Canadian customers. Otherwise, support risks postponing difficult decisions rather than resolving the commercial problem that made assistance necessary.
A Stronger Home Market Is Not Yet a Full Recovery
The room for growth at home should not be confused with an unlimited market. In its 2026 Steel Outlook, the OECD estimated that Canadian steel demand grew about 2.7% in 2025 and projected a further 0.9% increase in 2026. The latter is a forecast, not a completed annual result. It suggests that winning orders previously filled by imports may matter at least as much as relying on a broad construction or manufacturing boom.
The next evidence to watch is practical: actual domestic shipment volumes, factory profitability, sustained employment and completed investments. A rising Canadian market share is encouraging, but it cannot answer all four questions. Nor does replacing an American customer automatically make a mill immune to weak demand or changing trade rules. Canada’s steelmakers are building a more substantial business at home, with real examples in energy products and data-centre construction. The lasting achievement would be an industry that can keep skilled workers employed through the next trade disruption, rather than simply survive this one.
